DocumentsBylawApr 22, 2025Pages 117–121
Bylaw No. 2224 – City of Langford Tax Rates Bylaw No. 2224, 2025
Tax Rates Bylaw establishing the tax rates for 2025, presented for readings as part of the bylaw section.
Key facts
- Bylaw number: 2224 (Tax Rates Bylaw)
- Listed for: First, Second and Third Readings
- Purpose: Set municipal tax rates for 2025
Bylaw No. 2223 — Consolidated Financial Plan 2025-2029
Schedule "A" — Revenues and Expenditures (2025–2029)
| Item | 2025 | 2026 | 2027 | 2028 | 2029 |
|---|---|---|---|---|---|
| REVENUES: | |||||
| External Revenues | |||||
| Development Cost Charges | $2,325,000 | $4,635,000 | $1,250,000 | $2,600,000 | $1,100,000 |
| Developer Contributions | $2,500,000 | - | - | - | - |
| Other Capital Contributions | $8,325,000 | - | - | - | - |
| Municipal Property Taxes | $62,206,140 | $73,714,730 | $80,441,260 | $86,883,270 | $92,670,490 |
| Grants in Lieu | $200,000 | $204,000 | $208,000 | $212,000 | $216,000 |
| Utility Taxes | $568,460 | $584,310 | $600,960 | $618,100 | $635,740 |
| Parcel Taxes | $1,743,010 | $4,418,010 | $4,418,010 | $4,418,010 | $4,418,010 |
| Fees and Charges | $4,791,900 | $4,818,700 | $4,845,500 | $4,872,300 | $4,939,100 |
| Interest | $600,000 | $500,000 | $500,000 | $500,000 | $500,000 |
| Grants From Other Governments | $30,324,760 | $11,256,930 | $9,887,160 | $975,200 | $977,310 |
| Other Sources | $12,600,440 | $12,571,050 | $12,747,230 | $12,917,870 | $13,084,880 |
| Total External Revenues | $126,184,710 | $112,702,730 | $114,898,120 | $113,996,750 | $118,541,530 |
| EXPENDITURES: | |||||
| External Expenditures | |||||
| Operating Expenditures | $77,867,690 | $82,474,960 | $86,145,990 | $90,728,460 | $95,050,650 |
| Interest Payments on Debt | $946,500 | $2,901,500 | $2,901,500 | $2,901,500 | $2,901,500 |
| Capital Expenditures | $139,584,940 | $23,897,460 | $15,744,710 | $10,795,110 | $6,024,500 |
| Total External Expenditures | $218,399,130 | $109,273,920 | $104,792,200 | $104,425,070 | $103,976,650 |
| CHANGE IN NET FINANCIAL POSITION | ($92,214,420) | $3,428,810 | $10,105,920 | $9,571,680 | $14,564,880 |
| OTHER REVENUES: | |||||
| Borrowing Proceeds | $60,896,250 | $2,382,610 | $2,100,000 | $3,000,000 | $2,000,000 |
| OTHER EXPENDITURES: | |||||
| Principal Payments on Debt | $1,097,010 | $2,971,470 | $7,959,910 | $7,069,080 | $10,673,890 |
| TOTAL REVENUES LESS EXPENDITURES | $32,415,180 | -$2,839,950 | $4,246,010 | $5,502,600 | $5,890,990 |
INTERNAL TRANSFERS
Transfer from Reserve Funds
| Reserve Fund | 2025 | 2026 | 2027 | 2028 | 2029 |
|---|---|---|---|---|---|
| Affordable Housing | $751,820 | $269,730 | $272,720 | $275,800 | $275,800 |
| Capital Works & Equipment | $3,654,000 | $765,000 | $701,000 | $645,000 | $645,000 |
| Equipment Replacement | $1,380,100 | $1,945,780 | $760,270 | $319,570 | $220,390 |
| Parks & Open Space | $3,858,000 | - | - | - | - |
| Police Building Capital | $72,000 | $72,000 | $72,000 | $72,000 | $72,000 |
| General Capital Fund | $120,000 | $120,000 | $120,000 | $120,000 | $120,000 |
| General Operating | $7,177,290 | $1,811,850 | $1,197,710 | $3,418,110 | $1,207,500 |
| General Amenity | $3,295,840 | $2,140,000 | $823,000 | $800,000 | $800,000 |
| Growing Communities Fund | $18,055,300 | - | - | - | - |
| Transfer from Reserve Fund Total | $38,364,350 | $7,124,360 | $3,946,700 | $5,650,480 | $3,340,690 |
Less: Transfer to Reserve and Capital Funds
| Reserves | 2025 | 2026 | 2027 | 2028 | 2029 |
|---|---|---|---|---|---|
| Police Building Capital | $100,000 | $100,000 | $100,000 | $100,000 | $100,000 |
| Capital Works & Equipment | $1,405,000 | $1,405,000 | $1,405,000 | $1,405,000 | $1,405,000 |
| Equipment Replacement | $1,000,000 | $1,000,000 | $1,000,000 | $1,000,000 | $1,000,000 |
| General Capital Fund | $8,243,240 | $7,211,850 | $4,897,710 | $7,523,080 | $6,426,680 |
| Totals | $10,748,240 | $9,716,850 | $7,402,710 | $10,028,080 | $8,931,680 |
| Transfers from(to) Surplus | 2025 | 2026 | 2027 | 2028 | 2029 |
|---|---|---|---|---|---|
| Transfers from(to) Surplus | $4,565,310 | $365,000 | $285,000 | $200,000 | $200,000 |
| Transfers from(to) Reserve Accounts | $233,760 | ($612,460) | ($1,075,000) | ($1,325,000) | ($500,000) |
| TOTAL INTERNAL TRANSFERS | $32,415,180 | $2,839,950 | -$4,246,010 | -$5,502,600 | -$5,890,990 |
Schedule “B” — Revenue and Property Tax Disclosure
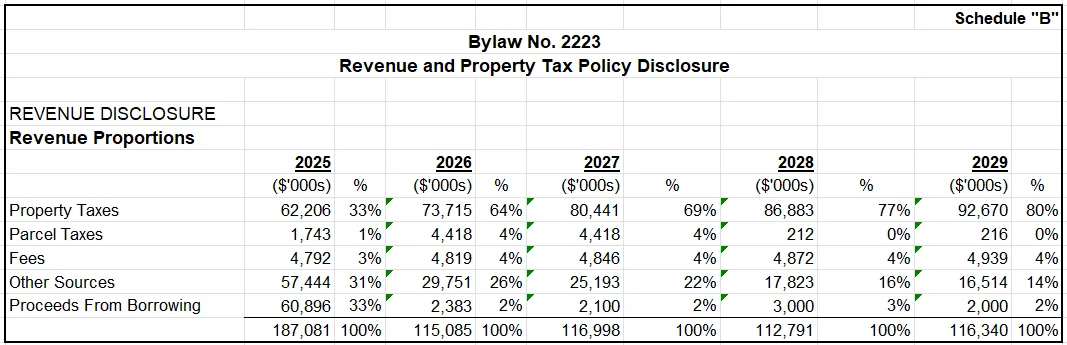
Other Sources includes grants from other governments and agencies, development contributions to capital, interest and penalties and miscellaneous sales of services.
Objectives and Policies
Property tax revenue is the City’s primary revenue source, and one which is heavily reliant on the residential class. Diversification of the tax base and generation of non-tax revenue are ongoing objectives.
Parcel Charges are comprised of local area service debt servicing costs for roads.
Fees & Charges are a tool used for cost recovery. Various fees are reviewed every 1-5 years to ensure that they are adequate to recover costs of providing specific services.
Other Sources will vary greatly from year to year as it includes such items as:
- Development cost charges used to fund DCC capital projects,
- Contributions from others for capital,
- Interest earned on funds invested,
- Grants, which are sought from other governments and government agencies, often to be leveraged with City funds,
- Casino revenue sharing income.
Proceeds from Borrowing – Debt is used where it makes sense such as for urgent projects or to leverage grants where internal funding is not available. Caution is necessary when considering debt as it commits future cash flows to debt payments, restricting the ability to use those funds to provide other services. The source of the debt payments needs to be considered as does the justification for advancing the project.
PROPERTY TAX DISCLOSURE
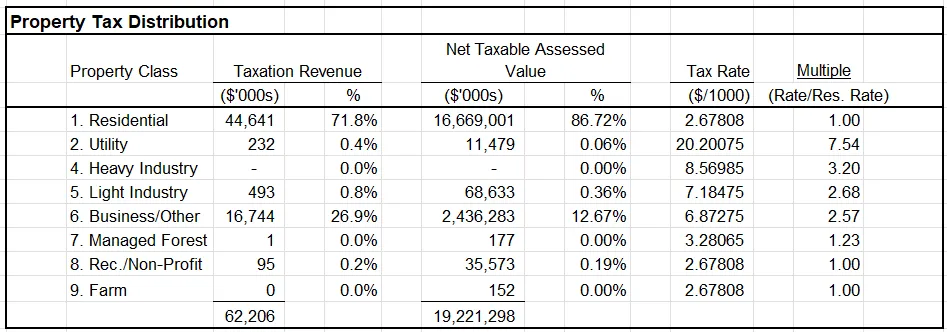
Property Tax Revenue Distribution
The table below presents tax revenue and tax rates based on the 2025 Revised Assessment Roll:
(Distribution table not reproduced in source text.)
Objectives and Policies
Council sets tax rates to maintain tax stability between property classes. Property class multiples are reviewed periodically to ensure that the burden of tax among property classes is not distorted by differing market value changes between classes.
Permissive Tax Exemptions
Policy with respect to permissive tax exemptions under section 224 of the Community Charter is that exemption will be considered where the organization has demonstrated proof of community access to citizens of Langford at a nominal charge and community benefit in the previous year.
Council supports the establishment of assisted living seniors’ housing in Langford and has granted 10-year exemptions to three such developments.
Council has established a revitalization tax exemption program under section 226 of the Community Charter which grants an exemption for eligible buildings for up to 10 years. An exemption certificate was issued for one property in 2021 for which the exemption expires in 2028.
CITY OF LANGFORD — BYLAW NO. 2224
A BYLAW TO LEVY PROPERTY VALUE TAXES TO MEET MUNICIPAL OBLIGATIONS FOR THE YEAR 2025.
WHEREAS, pursuant to Section 197 of the Community Charter, the Council must adopt a tax rate bylaw after the adoption of a financial plan, but before the fifteenth day of May;
NOW THEREFORE, the Council of the City of Langford, in open meeting assembled, enacts as follows:
- The following rates are hereby imposed and levied for the year 2025:
a) For all lawful general purposes of the Municipality on the assessed value of land and improvements taxable, for general municipal purposes, rates appearing in Column "A" of Schedule ‘A’ attached hereto and forming part hereof.
b) For all lawful purposes of the Regional District on the assessed value of lands and improvements taxable for general municipal purposes, rates appearing in Column "B" of Schedule ‘A’ attached hereto and forming a part hereof.
c) For all lawful purposes of the Regional Hospital District on the assessed value of land and improvements taxable for hospital purposes, rates appearing in Column "C" of Schedule ‘A’ attached hereto and forming a part hereof.
The minimum amount of taxation upon a parcel of real property shall be One Dollar ($1.00).
This bylaw may be cited for all purposes as "City of Langford Tax Rates Bylaw No. 2224, 2025."
READ A FIRST time on this day of April, 2025.
READ A SECOND time on this day of April, 2025.
READ A THIRD time on this day of April, 2025.
ADOPTED this day of May, 2025.
MAYOR
(Certified Correct)
CORPORATE OFFICER
Schedule ‘A’ to Bylaw 2224 — 2025 Tax Rates (Dollars of Tax Per $1000 Taxable Value)
| Description | Class | Municipal (A) | Regional District (B) | Regional Hospital District (C) |
|---|---|---|---|---|
| Residential | 1 | 2.67808 | 0.54218 | 0.12379 |
| Utilities | 2 | 20.20075 | 4.08967 | 0.43327 |
| Major Industry | 4 | 8.56985 | 1.73498 | 0.42090 |
| Light Industry | 5 | 7.18475 | 1.45456 | 0.42090 |
| Business/Other | 6 | 6.87275 | 1.39140 | 0.30329 |
| Managed Forest | 7 | 3.28065 | 0.66417 | 0.37138 |
| Recreational/Non Profit | 8 | 2.67808 | 0.54218 | 0.12379 |
| Farm | 9 | 2.67808 | 0.54218 | 0.12379 |