DocumentsAppendixMay 2, 2016Pages 30–50
Consolidated Financial Statements - City of Langford Year ended December 31, 2015 (Audited)
Audited consolidated financial statements for the City of Langford for the year ended December 31, 2015, including KPMG auditor's report and notes.
Key facts
- Auditor: KPMG LLP; audit opinion dated April 18, 2016 — statements present fairly in accordance with Canadian public sector accounting standards
- Accumulated surplus (end of year): $341,516,114 (2015)
- Cash and cash equivalents at year end: $16,560,675; Net debt: $(25,429,484)
- Significant items: Developer contributions and tangible capital asset additions; West Shore Parks & Rec Society consolidation note included
Consolidated Financial Statements
City of Langford
For the fiscal year ending December 31, 2015
Council and Officials
- Mayor: Stewart Young
- Councillors:
- Denise Blackwell
- Matt Sahlstrom
- Lanny Seaton
- Winnie Sifert
- Lillian Szpak
- Roger Wade
- Administrator: Jim Bowden, MPA
- Treasurer: Steve Ternent
- City Engineer: Michelle Mahovlich, M.Eng., P.Geo., P.Eng.
- City Planner: Matthew Baldwin, MCIP
- Fire Chief: Bob Beckett, MA
- Auditors: KPMG
- Solicitors: Young Anderson
- Bankers: Bank of Montreal
- Police: RCMP - West Shore
Contents
- Management's Responsibility for the Consolidated Financial Statements
- Independent Auditors' Report
- Consolidated Statement of Financial Position
- Consolidated Statement of Operations
- Consolidated Statement of Change in Net Debt
- Consolidated Statement of Cash Flows
- Notes to Consolidated Financial Statements
Management's Responsibility for the Consolidated Financial Statements
The accompanying consolidated financial statements of the City of Langford (the "City") are the responsibility of management and have been prepared in compliance with legislation, and in accordance with Canadian public sector accounting standards for local governments as recommended by the Public Sector Accounting Board of The Canadian Professional Accountants of Canada. A summary of the significant accounting policies are described in note 1 to the consolidated financial statements. The preparation of financial statements necessarily involves the use of estimates based on management's judgment, particularly when transactions affecting the current accounting period cannot be finalized with certainty until future periods.
The City's management maintains a system of internal controls designed to provide reasonable assurance that assets are safeguarded, transactions are properly authorized and recorded in compliance with legislative and regulatory requirements, and reliable financial information is available on a timely basis for preparation of the consolidated financial statements. These systems are monitored and evaluated by management.
The Administration and Finance Committee meets with management and the external auditors to review the consolidated financial statements and discuss any significant financial reporting or internal control matters prior to their approval of the consolidated financial statements.
The consolidated financial statements have been audited by KPMG LLP, independent external auditors appointed by the City. The accompanying Independent Auditors' Report outlines their responsibilities, the scope of their examination and their opinion on the City's consolidated financial statements.
Treasurer
Independent Auditors' Report
Chartered Professional Accountants
April 18, 2016
Victoria, Canada
(Full audit opinion text omitted for brevity in the table of contents; see full statements below.)
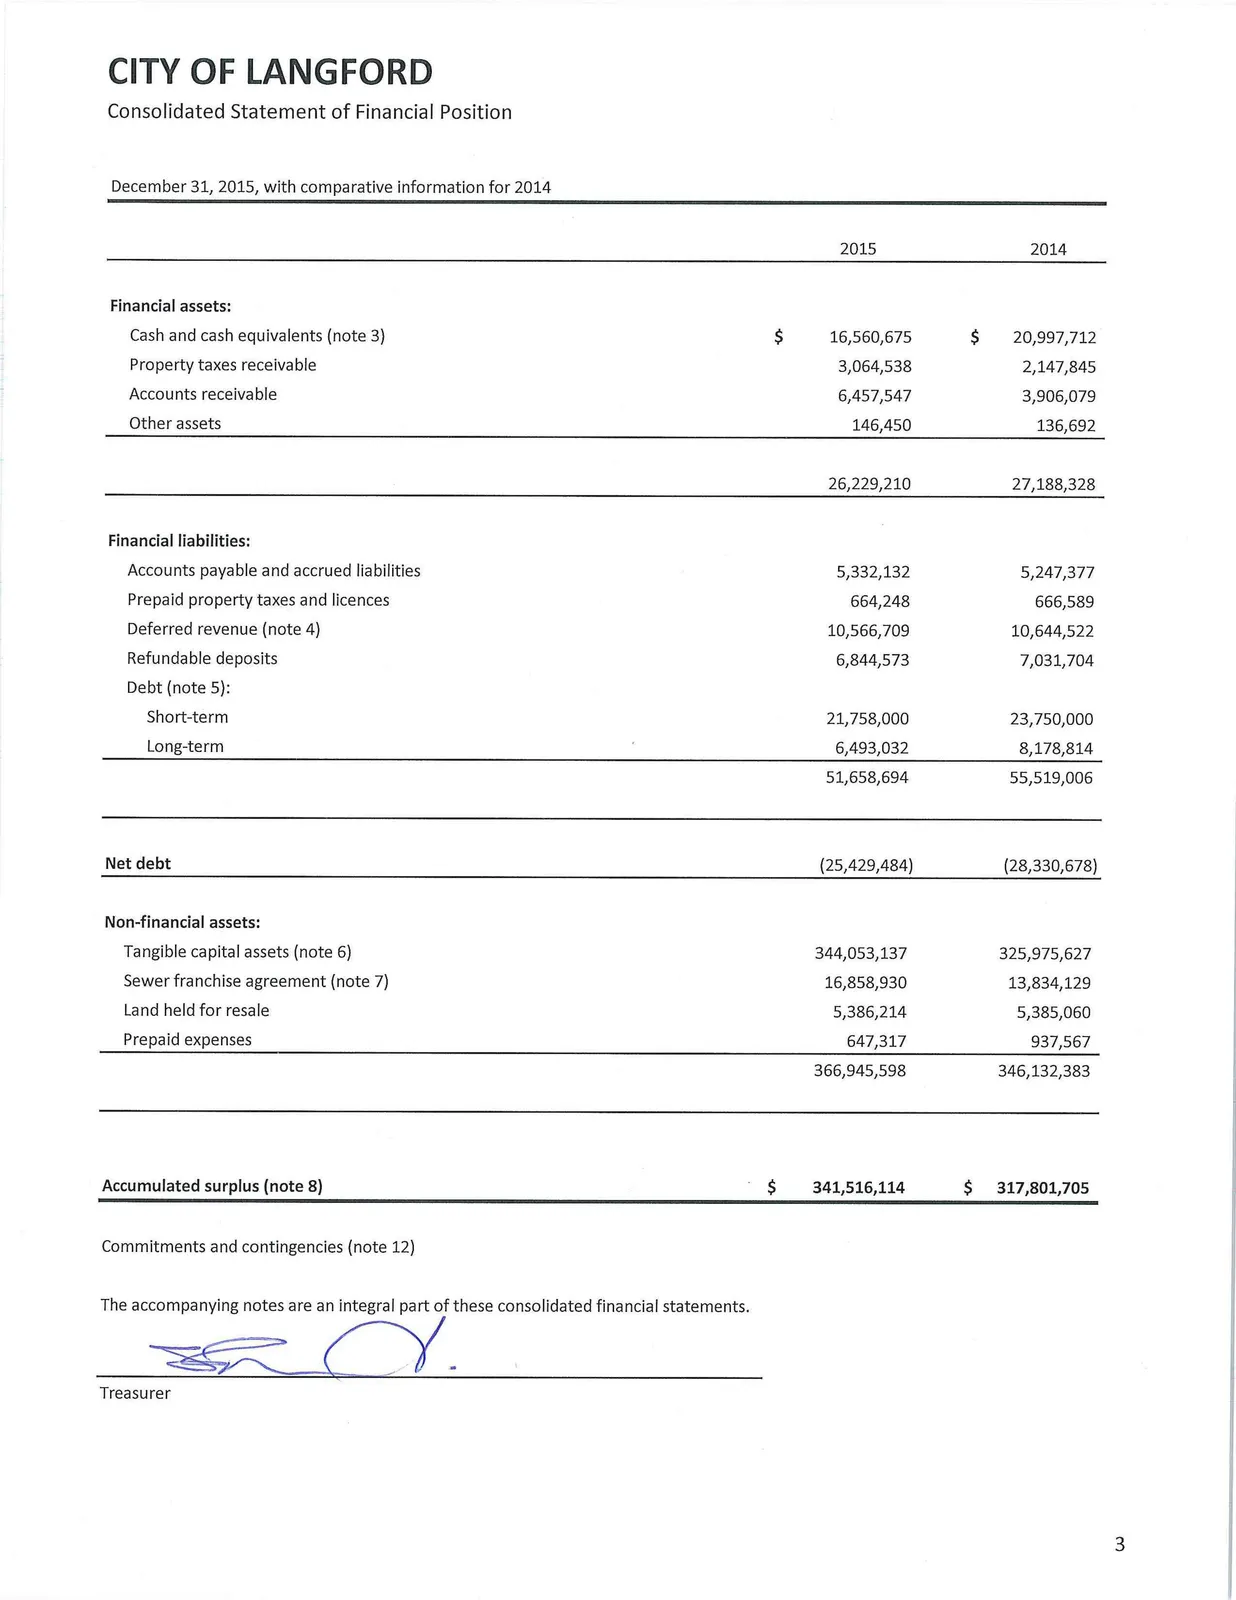
Consolidated Statement of Financial Position
December 31, 2015, with comparative information for 2014
| 2015 | 2014 | |
|---|---|---|
| Financial assets: | ||
| Cash and cash equivalents (note 3) | 16,560,675 $ | 20,997,712 $ |
| Property taxes receivable | 3,064,538 | 2,147,845 |
| Accounts receivable | 6,457,547 | 3,906,079 |
| Other assets | 146,450 | 136,692 |
| Total financial assets | 26,229,210 | 27,188,328 |
| Financial liabilities: | ||
| Accounts payable and accrued liabilities | 5,332,132 | 5,247,377 |
| Prepaid property taxes and licences | 664,248 | 666,589 |
| Deferred revenue (note 4) | 10,566,709 | 10,644,522 |
| Refundable deposits | 6,844,573 | 7,031,704 |
| Debt (note 5): | ||
| Short-term | 21,758,000 | 23,750,000 |
| Long-term | 6,493,032 | 8,178,814 |
| Total financial liabilities | 51,658,694 | 55,519,006 |
| Net debt | (25,429,484) | (28,330,678) |
| Non-financial assets: | ||
| Tangible capital assets (note 6) | 344,053,137 | 325,975,627 |
| Sewer franchise agreement (note 7) | 16,858,930 | 13,834,129 |
| Land held for resale | 5,386,214 | 5,385,060 |
| Prepaid expenses | 647,317 | 937,567 |
| Total non-financial assets | 366,945,598 | 346,132,383 |
| Accumulated surplus (note 8) | 341,516,114 $ | 317,801,705 $ |
Commitments and contingencies (note 12)
Consolidated Statement of Operations
December 31, 2015, with comparative information for 2014
| Description | Financial Plan (note 13) | 2015 | 2014 |
|---|---|---|---|
| Revenue: | |||
| Taxation, net (note 9) | 25,596,400 $ | 25,612,522 $ | 23,271,565 $ |
| Development cost charges | 5,901,200 | 3,356,342 | 413,419 |
| Sewer capital recovery fees | - | 3,637,868 | 2,436,949 |
| Utility charges | 5,000 | 5,000 | 5,000 |
| Other | 3,705,396 | 4,686,717 | 4,492,377 |
| Licences and permits | 1,780,500 | 2,345,918 | 1,951,112 |
| Penalties and interest | 433,000 | 354,522 | 413,543 |
| Government transfers (note 10) | 13,485,300 | 4,957,026 | 2,701,953 |
| Commercial leasing | 2,659,900 | 1,983,117 | 2,523,267 |
| Casino | 1,200,000 | 1,239,776 | 1,169,240 |
| Investment earnings | 170,000 | 208,014 | 274,384 |
| Developer and property owner contributions | 2,500,000 | 15,562,549 | 11,420,217 |
| Total revenue | 57,436,696 | 63,949,371 | 51,073,026 |
| Expenses: | |||
| General government services: | |||
| - Legislative | 465,500 | 330,590 | 391,411 |
| - Administrative | 2,243,900 | 2,753,319 | 2,513,332 |
| - Other | 1,497,600 | 1,438,596 | 1,244,526 |
| General government services total | 4,207,000 | 4,522,505 | 4,149,269 |
| Protective services: | |||
| - Police and bylaw enforcement | 6,570,900 | 6,724,855 | 6,654,710 |
| - Fire protection and emergency response | 2,706,100 | 3,134,723 | 2,977,807 |
| - Building inspection and other | 549,900 | 524,912 | 491,101 |
| Protective services total | 9,826,900 | 10,384,490 | 10,123,618 |
| Engineering and public works: | |||
| - Common services | 1,193,300 | 1,060,634 | 1,068,756 |
| - Land development services | 505,900 | 554,551 | 516,916 |
| - Roads, streets and storm drainage | 5,758,700 | 8,961,458 | 9,152,460 |
| Engineering and public works total | 7,457,900 | 10,576,643 | 10,738,132 |
| Community services: | |||
| - Environmental and development services | 1,051,700 | 933,389 | 779,065 |
| - Recreation and cultural services | 6,036,100 | 6,681,139 | 7,545,242 |
| - West Shore Parks and Recreation Society (note 14) | 5,265,231 | 6,409,322 | 5,251,685 |
| Community services total | 12,353,031 | 14,023,850 | 13,575,992 |
| Utility and enterprise services: | |||
| - Sewer infrastructure | - | 613,067 | 589,641 |
| - Sewer maintenance | - | 293 | 1,644 |
| - Debt interest | 124,500 | 114,114 | 139,717 |
| Utility and enterprise services total | 124,500 | 727,474 | 731,002 |
| Total expenses | 33,969,331 | 40,234,962 | 39,318,013 |
| Annual surplus | 23,467,365 | 23,714,409 | 11,755,013 |
| Accumulated surplus, beginning of year | 317,801,705 | 317,801,705 | 306,046,692 |
| Accumulated surplus, end of year | 341,269,070 | 341,516,114 | 317,801,705 |
Consolidated Statement of Changes in Net Debt
December 31, 2015, with comparative information for 2014
| Description | Financial Plan (note 13) | 2015 | 2014 |
|---|---|---|---|
| Annual surplus | 23,467,365 $ | 23,714,409 $ | 11,755,013 $ |
| Acquisition of tangible capital assets | (21,369,993) | (13,103,030) | (9,012,331) |
| Increase in land held for resale | - | (1,154) | (157,741) |
| Amortization of tangible capital assets | - | 6,774,852 | 6,523,484 |
| Loss on sale of tangible capital assets | - | 24,797 | 350,953 |
| Proceeds on sale of tangible capital assets | - | 920,284 | 491,452 |
| Sewer capital recovery fees | - | (3,637,868) | (2,436,949) |
| Developer contributions of tangible capital assets | - | (12,230,536) | (8,978,502) |
| Change in proportionate share of West Shore Parks & Rec Society | - | 149,190 | (418,107) |
| [Net] Consumption (acquisition) of prepaid expenses | - | 290,250 | (349,788) |
| Change in net financial assets (debt) | 2,097,372 | 2,901,194 | (2,232,516) |
| Net debt, beginning of year | (28,330,678) | (28,330,678) | (26,098,162) |
| Net debt, end of year | (26,233,306) | (25,429,484) | (28,330,678) |
Consolidated Statement of Cash Flows
December 31, 2015, with comparative information for 2014
| Cash provided by (used in): | 2015 | 2014 |
|---|---|---|
| Operating activities: | ||
| Annual surplus | 23,714,409 $ | 11,755,013 $ |
| Items not involving cash: | ||
| - Amortization of tangible capital assets | 6,774,852 | 6,523,484 |
| - Loss on sale of tangible capital assets | 24,797 | 350,953 |
| - Developer contributions of tangible capital assets | (12,230,536) | (8,978,502) |
| - Sewer capital recovery fees | (3,637,868) | (2,436,949) |
| - Actuarial adjustment on debt | (111,733) | (138,443) |
| - Change in proportionate share of West Shore Parks & Rec Society | 149,190 | (418,107) |
| Changes in non-cash operating assets and liabilities: | ||
| - Property taxes receivable | (916,693) | (609,664) |
| - Accounts receivable | (2,551,468) | 1,079,202 |
| - Other assets | (9,758) | (35,445) |
| - Accounts payable and accrued liabilities | 84,755 | (1,141,654) |
| - Prepaid property taxes and licences | (2,341) | 132,748 |
| - Deferred revenue | (77,813) | 1,002,270 |
| - Refundable deposits | (187,131) | 1,135,327 |
| - Prepaid expenses | 290,250 | (349,788) |
| Net cash from operating activities | 11,312,912 | 7,870,445 |
| Capital activities: | ||
| Acquisition of tangible capital assets | (13,103,030) | (9,012,331) |
| Increase in land held for resale | (1,154) | (157,741) |
| Proceeds on sale of tangible capital assets | 920,284 | 491,452 |
| Net cash used in capital activities | (12,183,900) | (8,678,620) |
| Financing activities: | ||
| Capital lease payments | - | (444,246) |
| Debt payments (West Shore Parks & Rec Society) | (37,202) | (46,035) |
| Debt payments | (3,528,847) | (3,426,806) |
| Net cash used in financing activities | (3,566,049) | (3,917,087) |
| Decrease in cash and cash equivalents | (4,437,037) | (4,725,262) |
| Cash and cash equivalents, beginning of year | 20,997,712 | 25,722,974 |
| Cash and cash equivalents, end of year | 16,560,675 | 20,997,712 |
| Supplemental cash flow information: | ||
| Cash paid for interest | 629,081 | 382,600 |
| Cash received from interest | 332,520 | 403,221 |
Notes to Consolidated Financial Statements
December 31, 2015, with comparative information for 2014
1. Significant accounting policies
(a) Reporting entity
The City of Langford (the "City") is incorporated and operates under the provisions of the British Columbia Local Government Act and the Community Charter of British Columbia.
(b) Basis of accounting
The consolidated financial statements of the City are prepared by management in accordance with Canadian public sector accounting standards for local governments as recommended by the Public Sector Accounting Board ("PSAB") of the Chartered Professional Accountants of Canada.
The consolidated financial statements include the assets, liabilities, revenues and expenses of the City. The consolidated financial statements also include the City's proportionate interest in the West Shore Parks and Recreation Society ("West Shore"), an organization jointly controlled by the City. The City does not administer any trust activities on behalf of external parties.
(c) Revenue recognition
The City follows the accrual method of accounting for revenues and expenses. Revenues are normally recognized in the year in which they are earned and measurable. Expenses are recognized as they are incurred and measurable.
Government transfers are recognized as revenues in the period in which events giving rise to the transfer occur, provided the transfers are authorized and any eligibility criteria have been met.
Property tax revenue is recognized on an accrual basis using approved tax rates and the anticipated assessment for the current year. Parcel tax revenues are recognized in the year that they are levied.
Investment income is reported as revenue in the period earned. When required by the funding government or related Act, investment income earned on deferred revenue is added to the investment and forms part of the deferred revenue balance.
(d) Deferred revenue
Deferred revenue includes grants, contributions and other amounts received from third parties pursuant to legislation, regulation and agreement which may only be used in certain programs, in the completion of specific work, or for the purchase of tangible capital assets. In addition, certain user charges and fees are collected for which the related services have yet to be performed. Revenue is recognized in the period when the related expenses are incurred, services performed, or the tangible capital assets are acquired thereby extinguishing any liability to the City.
Development cost charges are amounts which are restricted by government legislation or agreement with external parties. When qualifying expenditures are incurred, development cost charges are recognized as revenue in amounts which equal the associated expenses.
(e) Refundable deposits
Receipts restricted by third parties are deferred and reported as refundable deposits under certain circumstances. Refundable deposits are returned when the third party meets their obligations or the deposits are recognized as revenue when qualifying expenditures are incurred.
(f) Investment income
Investment income is reported as revenue in the period earned.
(g) Cash equivalents
Cash equivalents include short-term, highly liquid investments that are cashable on demand or have a term to maturity of 90 days or less at acquisition.
(h) Long-term debt
Long-term debt is recorded net of related repayments and actuarial earnings.
(i) Non-financial assets
(i) Tangible capital assets
Tangible capital assets are recorded at cost which includes amounts that are directly attributable to acquisition, construction, development or betterment of the asset. The cost, less residual value, of the tangible capital assets, excluding land, are amortized on a straight line basis over their estimated useful lives as follows:
| Asset | Useful life - years |
|---|---|
| Land improvements | 10-50 |
| Buildings | 25-70 |
| Vehicles, machinery, equipment | 5-25 |
| Sewer and storm infrastructure | 75-100 |
| Road infrastructure | 10-75 |
(ii) Works of art and cultural and historic assets
Works of art and cultural and historic assets are not recorded as assets in these financial statements.
(iii) Leased tangible capital assets
Leases which transfer substantially all of the benefits and risks incidental to ownership of property are accounted for as leased tangible capital assets. All other leases are accounted for as operating leases and the related payments are charged to expenses as incurred.
(iv) Inventory of supplies
Inventory of supplies held for consumption is recorded at the lower of cost and replacement cost.
(j) Employee benefits
The City and its employees make contributions to the Municipal Pension Plan. These contributions are expensed as incurred.
(k) Use of estimates
The preparation of financial statements requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities, disclosure of contingent assets and liabilities at the date of the financial statements, and the reported amounts of revenues and expenses during the period.
(l) Contributions of tangible capital assets
Tangible capital assets received as contributions are recorded at their fair value and are recorded as revenue at the date of receipt.
2. Adoption of new accounting policy
The City of Langford adopted Public Sector Accounting Board Standard PS 3260 Liability for Contaminated Sites effective January 1, 2015. The City adopted this standard on a retroactive basis and there were no adjustments as a result of the adoption of this standard.
3. Cash and cash equivalents
| 2015 | 2014 | |
|---|---|---|
| West Shore Parks and Recreation Society | 1,569,819 $ | 1,528,689 $ |
| Cash | 6,160,233 | 2,469,023 |
| Bank overdraft | (1,169,377) | - |
| Term deposits | 10,000,000 | 17,000,000 |
| Total cash and cash equivalents | 16,560,675 | 20,997,712 |
The City has an approved operating line of credit of $7,500,000.
4. Deferred revenue
| 2015 | 2014 | |
|---|---|---|
| Development cost charges | 9,288,738 $ | 9,579,792 $ |
| Hotel room tax | 663,938 | 483,856 |
| Other | 614,033 | 580,874 |
| Total deferred revenue | 10,566,709 | 10,644,522 |
Development cost charges details:
| 2015 | 2014 | |
|---|---|---|
| Opening balance of unspent funds | 9,579,792 $ | 8,274,026 $ |
| Add: Development cost charges received during the year | 2,979,335 | 1,620,348 |
| Add: Interest earned | 85,953 | 98,837 |
| Subtotal | 12,645,080 | 9,993,211 |
| Less amount spent on projects and recorded as revenue | (3,356,342) | (413,419) |
| Closing balance | 9,288,738 | 9,579,792 |
Deferred revenue, reported on the consolidated statement of financial position, is comprised of the above.
5. Debt
(a) Short-term debt is comprised of an interim financing facility through the TD Bank due on demand which bears interest at the Bankers Acceptance Rate plus stamping fee of 75 basis points.
(b) Long-term debt consists of the following:
| Creditor | 2015 | 2014 |
|---|---|---|
| Municipal Finance Authority ("MFA") | 49,299 $ | 304,428 $ |
| West Shore Parks & Rec Society five year fixed rate loan | - | 37,202 |
| TD Bank | 6,443,733 | 7,837,184 |
| Total long-term debt | 6,493,032 | 8,178,814 |
Long-term debt from the TD Bank consists of five year floating rate term loans maturing from 2017 to 2021, with a current interest rate of 1.61%.
Long-term debt through the MFA is presented net of repayments and actuarial earnings. The gross value of debenture debt at December 31, 2015 is $2,918,000 (2014 - $4,643,000). The accumulation of principal repayments and actuarial earnings allocated to the City as of December 31, 2015 is $2,868,702 (2014 - $4,338,572).
(c) Principal payments on long term debt and budgeted repayments on short-term debt for the next five years are as follows:
| Year | Principal payments |
|---|---|
| 2016 | 2,399,100 $ |
| 2017 | 2,826,800 |
| 2018 | 2,081,800 |
| 2019 | 1,490,600 |
| 2020 | 1,521,500 |
6. Tangible capital assets
(a) Assets under construction have a value of $10,330,582 (2014 - $3,908,536) and have not yet been amortized. Amortization will commence when the asset is put into service.
(b) Contributed tangible capital assets have been recognized at fair market value at the date of contribution. The value of contributed capital assets received during the year is $12,230,536 (2014 - $8,978,502) comprised of land $7,271,605 (2014 - $4,069,876), land improvements $106,375 (2014 - $20,172), buildings $NIL (2014 - $NIL), sewer and storm infrastructure $2,113,823 (2014 - $1,612,867) and roads infrastructure $2,738,733 (2014 - $3,275,587).
(c) The City manages works of art and non-operational historical cultural assets which are not recorded as tangible capital assets.
(d) No tangible capital assets were written down in 2015 or 2014.
(e) The City's proportionate share of West Shore Parks and Recreation Society assets includes land, buildings, and equipment which are subject to amortization policies consistent with those of the City.
Tangible capital assets — Cost, Accumulated Amortization and Net Book Value (2015 vs 2014)
| Category | Land | Land Improvements | Buildings | Machinery & Equipment | Sewer & Storm Infrastructure | Roads Infrastructure | Assets Under Construction | West Shore Parks & Recreation Society | Total 2015 | Total 2014 |
|---|---|---|---|---|---|---|---|---|---|---|
| Cost - Opening | 130,292,040 | 15,616,625 | 31,975,062 | 11,532,696 | 45,635,219 | 113,438,143 | 3,908,536 | 31,760,845 | 384,159,166 | 366,714,138 |
| Additions | 10,749,968 | 386,690 | 749,860 | 321,566 | 2,113,823 | 4,447,286 | 6,527,921 | 142,327 | 25,439,441 | 18,944,437 |
| Disposals | (774,534) | - | - | (230,217) | - | (199,304) | (105,875) | (47,047) | (1,356,977) | (2,042,528) |
| Change in share | - | - | - | - | - | - | - | (198,379) | (198,379) | 543,119 |
| Balance, end of year (Cost) | 140,267,474 | 16,003,315 | 32,724,922 | 11,624,045 | 47,749,042 | 117,686,125 | 10,330,582 | 31,657,746 | 408,043,251 | 384,159,166 |
| Accum. Amortization - Opening | - | 4,143,001 | 5,142,585 | 5,457,989 | 7,971,905 | 27,592,689 | - | 7,875,370 | 58,183,539 | 52,371,203 |
| Disposals | - | - | - | (230,217) | - | (31,763) | - | (44,041) | (306,021) | (246,519) |
| Amortization | - | 663,843 | 651,665 | 798,930 | 780,629 | 2,671,142 | - | 595,576 | 6,161,785 | 5,933,843 |
| Change in share | - | - | - | - | - | - | - | (49,189) | (49,189) | 125,012 |
| Balance, end of year (Accum. Amort.) | - | 4,806,844 | 5,794,250 | 6,026,702 | 8,752,534 | 30,232,068 | - | 8,377,716 | 63,990,114 | 58,183,539 |
| Net book value, end of year | 140,267,474 | 11,196,471 | 26,930,672 | 5,597,343 | 38,996,508 | 87,454,057 | 10,330,582 | 23,280,030 | 344,053,137 | 325,975,627 |
7. Sewer franchise agreement
During 2004, the City entered into a franchise and partnering agreement with West Shore Environmental Services Inc. ("WSES") and Terasen Utility Services Inc. The term of the agreement is 21 years, with a single 21 year renewal. Under the agreement, the City grants an exclusive franchise to WSES to design, construct, finance, own, and operate and maintain sanitary sewers in the City. The City also grants an exemption from municipal property tax for sewer infrastructure and WSES has been granted an Order in Council to extend that exemption to property taxes for all other jurisdictions. Upon termination of the agreement, the sewer infrastructure constructed by WSES will be acquired by the City for a nominal payment.
WSES will recover its capital costs by imposition of a sewer capital recovery fee ("SCRF") on owners of property who wish to connect to the sewer. WSES will also bill and collect all user fees. Fees were frozen for five years ended in 2009. WSES will pay the City franchise fees that are estimated to total $11 million over the 21 year term of the agreement.
The City records the costs of sewer infrastructure constructed by WSES $905,271 (2014 - $2,374,329) and corresponding remaining cost to be recovered. The remaining cost to be recovered is reduced as SCRF's are collected by WSES.
The cost of WSES sewer infrastructure, less residual value, is amortized on a straight line basis over their estimated useful lives, 60 to 70 years.
Sewer franchise agreement — Summary
| Opening | Increase | Decrease | Increase | Closing | |
|---|---|---|---|---|---|
| WSES sewer infrastructure - Cost | 36,737,685 $ | 1,298,597 | (393,326) | 1,298,597 | 37,642,956 |
| Accumulated amortization | (4,839,332) | (613,067) | - | (613,067) | (5,452,399) |
| Net | 31,898,353 | 685,530 | (393,326) | 685,530 | 32,190,557 |
| Remaining cost to be recovered | (18,064,224) | (1,298,597) | 4,031,194 | (1,298,597) | (15,331,627) |
| Net (Sewer franchise agreement) | 13,834,129 | (613,067) | 3,637,868 | (613,067) | 16,858,930 |
8. Accumulated surplus
Accumulated surplus consists of individual fund surplus and reserves and reserve funds as follows:
| Description | 2015 | 2014 |
|---|---|---|
| Surplus: | ||
| Invested in tangible capital assets | 332,661,035 $ | 307,880,942 $ |
| Invested in land held for resale | 5,386,214 | 5,385,060 |
| Other | (7,505,132) | (5,986,122) |
| Total surplus | 330,542,117 | 307,279,880 |
| Reserves set aside by Council: | ||
| Future operational contingencies | 276,105 | 247,900 |
| Federal Gas Tax | 827,870 | 1,462,826 |
| West Shore Parks & Rec Society | 858,300 | 930,894 |
| Total reserves | 1,962,275 | 2,641,620 |
| Reserve funds set aside for specific purposes by Council: | ||
| Capital works | 1,531,820 | 1,360,237 |
| Affordable housing | 999,498 | 976,731 |
| Parks and open space | 2,143,353 | 1,756,988 |
| Parkland improvement | 2,875 | 52,608 |
| General amenity | 2,198,060 | 2,020,262 |
| Equipment replacement | 712,782 | 441,873 |
| Sidewalk capital | 98,998 | 85,261 |
| Bear Mountain fire hall | 1,109,377 | 973,101 |
| Special police capital | 178,325 | 176,819 |
| Downtown parking | 36,634 | 36,325 |
| Total reserve funds | 9,011,722 | 7,880,205 |
| Accumulated surplus (total) | 341,516,114 | 317,801,705 |
9. Taxation
Taxation revenue, reported on the consolidated statement of operations, is comprised of the following:
| Description | 2015 | 2014 |
|---|---|---|
| General | 23,485,325 $ | 22,784,727 $ |
| Parcel tax | 1,629,410 | - |
| Revenue in lieu of taxes | 104,134 | 99,349 |
| Collections for other governments | 26,666,973 | 25,931,212 |
| 1% utility taxes | 393,653 | 387,489 |
| Total taxation | 52,279,495 | 49,202,777 |
| Less taxes levied for other authorities: | ||
| Capital Regional District - General Operating | 4,831,876 | 4,108,539 |
| Revenue in lieu of taxes | 85,762 | 85,687 |
| Capital Regional Hospital District | 2,272,620 | 2,304,293 |
| School Authorities | 16,390,873 | 16,352,340 |
| BC Assessment Authority | 478,270 | 487,931 |
| Municipal Finance Authority | 1,526 | 1,497 |
| BC Transit | 2,606,046 | 2,590,925 |
| Total levies for other authorities | 26,666,973 | 25,931,212 |
| Net taxation revenue (reported) | 25,612,522 | 23,271,565 |
10. Government transfers
The City recognizes the transfer of government funding as revenue when received and all related eligibility criteria and stipulations have been satisfied.
| 2015 | 2014 | |
|---|---|---|
| Operating transfers: | ||
| Federal | 10,017 $ | 11,796 $ |
| Provincial | 273,500 | 171,776 |
| Other | 632,697 | 438,617 |
| Total operating transfers | 916,214 | 622,189 |
| Capital transfers: | ||
| Federal | 2,419,051 | 1,462,826 |
| Provincial | 1,378,333 | 616,938 |
| Other | 243,428 | - |
| Total capital transfers | 4,040,812 | 2,079,764 |
| Total government transfers (Revenue) | 4,957,026 | 2,701,953 |
11. Municipal pension plan
The City and its employees contribute to the Municipal Pension Plan (the "Plan"), a jointly trusteed pension plan. The pension plan is a multi-employer defined benefit pension plan. The most recent actuarial valuation as at December 31, 2012 indicated a $1,370 million funding deficit for basic pension benefits. The next valuation will be as at December 31, 2015 with results available later in 2016.
Employers participating in the Plan record their pension expense as the amount of employer contributions made during the fiscal year (defined contribution pension plan accounting). The City paid $629,637 (2014 - $563,627) for employer contributions to the Plan in fiscal 2015.
12. Commitments and contingencies
(a) Contingent liabilities: There are several lawsuits pending in which the City is involved. It is considered that the potential claims against the City resulting from such litigation will be covered by insurance and therefore will not materially affect the consolidated financial statements of the City.
(b) Municipal Finance Authority contingent demand notes: Under borrowing arrangements with the MFA, the City is required to lodge security by means of demand notes and interest-bearing cash deposits. At December 31, 2015 there were contingent demand notes of $23,459 which are not included in the financial statements of the City.
(c) Litigation liability: See (a) above.
(d) Commitments: The City entered into a long-term contract with the Royal Canadian Mounted Police (RCMP) for the provision of police services effective October 1, 1994. Under the terms of this contract, the City is responsible for 90% of policing costs. The 2016 estimated cost of this contract is $5,309,500.
On February 7, 2013, the City entered into a purchase of service agreement with the YMCA/YWCA of Greater Victoria to provide access for Langford residents to an aquatic facility to be built in Langford. The facility is expected to open later in 2016 at which time the City agrees to pay $750,000 per year to be indexed by population every two years from the opening date to a maximum of $950,000 per year for a period of 25 years.
13. Financial plan
The financial plan data presented in these consolidated financial statements is based upon the 2015 operating and capital financial plans approved by Council on May 4, 2015. Amortization expense was not contemplated on development of the financial plan and, as such, has not been included. The chart below reconciles the approved financial plan to figures reported in these consolidated financial statements.
| Revenues | Amount |
|---|---|
| Operating | 38,001,200 $ |
| Capital | 36,997,100 |
| West Shore Parks & Rec Society | 2,826,996 |
| Less: Transfers from own funds | (11,666,900) |
| Proceeds on debt issue | 8,721,700 |
| Total revenue | 57,436,696 |
| Expenses | Amount |
|---|---|
| Operating | 38,001,200 $ |
| Capital | 36,997,100 |
| West Shore Parks & Rec Society | 2,844,731 |
| Less: Capital expenditures | (36,997,100) |
| Transfer to own funds | (4,399,500) |
| Debt principal payments | (2,477,100) |
| Total expenses | 33,969,331 |
Annual surplus (Financial plan) = 23,467,365 $
14. West Shore Parks and Recreation Society
(a) Capital asset transfer:
The Capital Regional District (the "CRD") transferred the lands and facilities comprising the Juan de Fuca Recreation Centre to the municipal members effective January 2, 2002. The lands and facilities were transferred to the Municipalities in their proportionate share, as specified in the Co-Owners' Agreement. For 2015, the City's share of improvements purchased by the Society on its behalf is $NIL.
(b) Consolidation:
Financial results and budget for the Society are consolidated into the City's financial statements proportionately, based on the cost sharing formula outlined in the Members' Agreement. In 2015, the City's proportion for consolidation purposes was 49.96% (2014 - 50.27%).
Condensed financial information for the Society is as follows:
| 2015 | 2014 | |
|---|---|---|
| Financial assets | 3,414,023 $ | 3,316,805 $ |
| Financial liabilities | 2,422,204 | 2,106,272 |
| Net financial assets | 991,819 | 1,210,533 |
| Non-financial assets | 905,600 | 853,693 |
| Accumulated surplus | 1,897,419 | 2,064,226 |
| Invested in tangible capital assets | 892,651 | 842,168 |
| Reserve funds | 1,718,043 | 2,041,890 |
| Other | (713,275) | (819,832) |
| Accumulated surplus (Society) | 1,897,419 | 2,064,226 |
| Revenues (Society) | 6,433,559 | 5,862,973 |
| Requisition from members | 4,844,916 | 4,762,205 |
| Total revenues | 11,278,475 | 10,625,178 |
| Expenses (Society) | 6,600,366 | 5,559,653 |
| Requisition from members | 4,844,916 | 4,762,205 |
| Total expenses | 11,445,282 | 10,321,858 |
| Annual surplus (deficit) | (166,807) | 303,320 |
Because the cost sharing formula in the Members' Agreement produces different cost shares for the members from year-to-year, there is a gain or loss on the opening fund balances. In 2015, the City recorded a loss of $149,190.
15. Segmented information
The City is a diversified municipal government institution that provides a wide range of services to its citizens, including General Government Services, Protective Services, Engineering and Public Works Services, Community Services and Utility and Enterprise Services. Service Areas were created for the purpose of recording specific activities to attain certain objectives in accordance with regulations, restrictions or limitations.
The accounting policies used in these segments are consistent with those followed in the preparation of the financial statements as disclosed in Note 1. Taxation and grants in lieu of taxes are apportioned to the functions based on their share of the net budgeted expenditures in the Financial Plan.
2015 Segmented Information (Revenue and Expenses)
| Category | General Government Services | Protective Services | Engineering and Public Works | Community Services | Utility and Enterprise Services | Total |
|---|---|---|---|---|---|---|
| Revenue: | 63,949,371 $ | |||||
| Taxation | 4,607,800 | 8,408,600 | 5,898,700 | 6,697,422 | - | 25,612,522 |
| Utility charges | - | - | - | - | 5,000 | 5,000 |
| Government transfers | 1,897,701 | 388,660 | 2,565,009 | 105,656 | - | 4,957,026 |
| Commercial leasing | 31,473 | 184,222 | - | 1,767,422 | - | 1,983,117 |
| Other | 1,841,692 | 50,403 | 56,860 | 3,300,298 | 3,637,868 | 8,887,121 |
| Licences and permits | 15,769 | 1,419,077 | 532,245 | 378,827 | - | 2,345,918 |
| Developer and property owner contributions | 749,700 | - | 10,959,026 | 1,740,000 | 2,113,823 | 15,562,549 |
| Development cost charges | - | - | 3,182,901 | 173,441 | - | 3,356,342 |
| Casino | 319,400 | - | 920,376 | - | - | 1,239,776 |
| Total Revenue | 9,463,535 | 10,450,962 | 24,115,117 | 14,163,066 | 5,756,691 | 63,949,371 |
| Expenses: | 40,234,962 | |||||
| Salaries, wages and employee benefits | 2,295,327 | 3,221,285 | 1,784,814 | 2,852,331 | 293 | 10,154,050 |
| Contracted and general services | 998,436 | 5,970,045 | 4,366,131 | 6,767,027 | - | 18,101,639 |
| Materials, goods, supplies and utilities | 520,146 | 557,368 | 512,022 | 1,017,265 | - | 2,606,801 |
| Other | 401,012 | 245,492 | 569,211 | 1,267,791 | 114,114 | 2,597,620 |
| Amortization | 307,584 | 390,300 | 3,344,465 | 2,119,436 | 613,067 | 6,774,852 |
| Total Expenses | 4,522,505 | 10,384,490 | 10,576,643 | 14,023,850 | 727,474 | 40,234,962 |
| Annual surplus (deficit) | 4,941,030 | 66,472 | 13,538,474 | 139,216 | 5,029,217 | 23,714,409 |
2014 Segmented Information (Revenue and Expenses)
| Category | General Government Services | Protective Services | Engineering and Public Works | Community Services | Utility and Enterprise Services | Total |
|---|---|---|---|---|---|---|
| Revenue: | 51,073,026 $ | |||||
| Taxation | 4,214,000 | 7,882,465 | 4,048,600 | 6,272,600 | 853,900 | 23,271,565 |
| Utility charges | - | - | - | - | 5,000 | 5,000 |
| Government transfers | 1,804,520 | 297,386 | 588,251 | 11,796 | - | 2,701,953 |
| Commercial leasing | 28,269 | 196,093 | - | 2,298,905 | - | 2,523,267 |
| Other | 1,700,652 | 193,201 | 193,739 | 3,092,712 | 2,436,949 | 7,617,253 |
| Licences and permits | 116,475 | 953,045 | 463,017 | 418,575 | - | 1,951,112 |
| Developer and property owner contributions | 860,435 | 52,500 | 7,786,991 | 1,099,124 | 1,621,167 | 11,420,217 |
| Development cost charges | - | - | 150,340 | 263,079 | - | 413,419 |
| Casino | 329,984 | - | 839,256 | - | - | 1,169,240 |
| Total Revenue | 9,054,335 | 9,574,690 | 14,070,194 | 13,456,791 | 4,917,016 | 51,073,026 |
| Expenses: | 39,318,013 | |||||
| Salaries, wages and employee benefits | 2,198,419 | 3,047,179 | 1,729,887 | 2,339,759 | 1,644 | 9,316,888 |
| Contracted and general services | 814,312 | 5,844,431 | 4,265,355 | 7,031,141 | - | 17,955,239 |
| Materials, goods, supplies and utilities | 479,907 | 440,509 | 438,624 | 780,515 | - | 2,139,555 |
| Other | 357,644 | 411,218 | 1,103,271 | 1,370,997 | 139,717 | 3,382,847 |
| Amortization | 298,987 | 380,281 | 3,200,995 | 2,053,580 | 589,641 | 6,523,484 |
| Total Expenses | 4,149,269 | 10,123,618 | 10,738,132 | 13,575,992 | 731,002 | 39,318,013 |
| Annual surplus (deficit) | 4,905,066 | (548,928) | 3,332,062 | (119,201) | 4,186,014 | 11,755,013 |
(End of extracted content for pages 30–50.)
Document Images
(3)